As shown in Madeleine’s video
While they fight, SAVE $6,000 in your first year

US EditionCanadian Edition
The little-known Medicare, tax and insurance rules that quietly put money back in retirees’ pockets. The little-known pension, tax and prescription rules that quietly put money back in retirees’ pockets. Written down step by step, in one large-print manual.
Earn the $47 back in your first month.Or get every penny back.
Instant access · Pay once · Yours forever
Read the math →I.
The Manual
One manual. Twenty-three moves. Six thousand dollars in your first year.One manual. Twenty-one moves. Six thousand dollars in your first year.
Medicare, taxes, insurance, hearing aids, groceries, phone, TV and internet. Twelve moves to save, eleven to protect what you keep. Each one with the official rule, the deadline and the step-by-step. Start this week with a letter that is already in your mailbox.Pensions, taxes, prescriptions, hearing aids, savings, phone, TV and internet. Ten moves to save, eleven to protect what you keep. Each one with the official rule, the deadline and the step-by-step. Start this week with your last three tax returns.
Large-print ebook · 140 pages · 2026–2027 EditionLarge-print ebook · 133 pages · 2026–2027 Edition
The complete playbook to save $6,000 in your first year.
The December 7 drug-plan window. The Medigap birthday window. The 2022 hearing-aid rule. The new-customer re-rate. The state’s own insurance price list. The cable fees that aren’t taxes. The FCC price label. Free tax filing at 60+. The property-tax cap you have to apply for.The late pension split (the CRA decides whether to accept it). Pension splitting every year. Medical bills on the right return. Ontario’s hearing-aid help. The 100-day fill. Your drug deductible, paid back. The 0.01% savings trap. The cheaper brand on the same network. The C$25 TV package. Every rule checked against official sources in October 2026, with exactly what to do. Earn the $47 back inside your first month.
What you get for $47:
- The Home Front Manual — 140-page large-print ebook, 23 numbered moves133-page large-print ebook, 21 numbered moves, in Canadian dollars, official sources, step-by-step$67
- The First-Month Payback Plan — the quick moves you make this week that earn the $47 back on your next bills$19
- The Family Workbook — 20 fillable pages: medication lists, accounts map, emergency plan and the Fridge Sheet$19
- The 20-Minute Worksheet — see exactly what each move is worth in your own house$14
- Free updates — every revision, including the January 2027 refresh, no extra charge$21
- Total value$140
- You pay today$47
Instant access · Pay once · Yours forever
Secure checkout · PayPal · Visa · Mastercard · 30-day refund
II.
The Math
Where the $6,942 comes from.Where the $5,742 comes from.Where the C$7,043 comes from.
Pull up your last 12 months of bills and follow along. This is our example couple: retired in Maryland, both 68, on Original Medicare.This is our example couple: retired in Ontario, both 68, one of them with most of the workplace pension. Every line comes straight from the manual’s Ledger.
- The December 7 drug-plan windowEvery year$1,200
- The Medigap birthday windowEvery year$353
- The 2022 hearing-aid ruleOne time · one pair$2,820
- The car-insurance new-customer re-rateEvery year$461
- The state’s own home-insurance price listEvery year$400
- Same phones, same towers, lower planEvery year$350
- The cable fees that aren’t taxesEvery year$240
- The FCC internet price labelEvery year$180
- Free tax filing at 60+Every year$220
- The property-tax cap you apply forYear one$115
- Same brands, a third cheaperEvery year$421
- The federal warranty ruleEvery year$182
- The next 12 months$6,942
- The next 12 months$5,742
- The late pension split, 2023–2025One time · the CRA decidesC$3,190
- Pension splitting every yearEvery yearC$1,182
- Medical bills on the right returnEvery yearC$265
- Ontario’s hearing-aid helpOne timeC$1,000
- The 100-day prescription fillEvery yearC$210
- Your drug deductible, paid backEvery yearC$200
- Savings off 0.01%, same bankEvery yearC$325
- Same network, cheaper brandEvery yearC$264
- The internet price already advertisedEvery yearC$240
- The C$25 TV packageEvery yearC$167
- The next 12 monthsC$7,043
Every number has a move in the Manual, with the official source and the steps.
The first month
The quickest moves start paying on your very next bills.
- Same phones, same towers, lower plan$29/mo
- The cable fees that aren’t taxes$20/mo
- The FCC internet price label$15/mo
- Same brands, a third cheaper$35/mo
- Every month$99
- Savings off 0.01%, same bankC$27/mo
- Same network, cheaper brandC$22/mo
- The internet price already advertisedC$20/mo
- The C$25 TV packageC$14/mo
- The 100-day prescription fillC$18/mo
- Every monthC$101
That is the Manual paid for in month one. And the December 7 drug-plan window closes on its own schedule: miss it, and it waits a full year.And the late pension split needs the forms in the mail by November 30, 2026 for all three refunds to arrive within 12 months. The CRA decides whether to accept it.
Instant access · Pay once · Yours forever
III.
Why you never heard of it
The rules already set money aside for you. Almost nobody tells you it’s there.
Their fight is pushing prices up, and you can’t stop any of it. But windows open once a year, federal rules change quietly, credits wait for you to apply, and deadlines close without a reminder.
- A 30-day window opens on your birthday. In Maryland it lets you keep the exact same Medigap coverage for less, with no health questions.$353 a year for our example couple
- Since 2022, a federal rule lets adults buy hearing aids off the shelf, without the clinic price. Most people still don’t know.$2,820 on one pair
- A letter that arrived by September 30 shows whether your drug plan costs more on January 1. After December 7, it’s too late to act for 2027.$1,200 a year for our example couple
- Maryland’s property-tax cap is not automatic. If you never applied, you aren’t getting it, and it grows every year.
- Couples who missed pension splitting may be able to go back three years. The CRA decides whether to accept it.C$3,190 for our example couple
- Ontario pays up to C$1,000 toward hearing aids, but only if the steps happen in the right order. Buy first, and you get nothing.
- The six big banks post 0.01% on ordinary savings and 2.45% on a one-year GIC, at the same counter.C$325 a year for our example couple
- The rules cap a basic TV package at C$25 a month. The average subscriber pays C$58.90.C$167 a year for our example couple
Nobody makes money telling you. Companies have no reason to point you to a cheaper option, and no government office calls when a window opens. It’s all public, buried in rate guides, federal rules and agency fine print.
So we dug through it for you.
IV.
Reader results
What people did with the manual.
IV.
Inside the Manual
A few of the things you’ll find.
- p. 28The one letter that tells you whether your drug plan is about to cost you more next year, and the date after which it’s too late to act.
- p. 32The yearly “birthday window”: the same Medigap coverage for $353 less, with no health questions asked.
- p. 37The 2022 federal rule most people still don’t know about, worth $2,820 on one pair, plus the four red flags that mean see a doctor first.
- p. 41Why 20 years with one insurer can cost you more, and the one request that asks for the price a new customer would get.
- p. 45The state’s own price list showing one insurer charging 5.6 times another for the identical home policy.
- p. 53The “Broadcast TV fee” that looks like a tax but isn’t. On one Maryland bill it’s $30.25 a month.
- p. 61Free tax filing aimed at people 60 and older, with no income test.
- p. 72The federal law that says the dealer can’t void your warranty because routine service was done somewhere else.
- Part TwoEleven moves that guard what you keep: how a couple can keep $500,000 at one bank fully insured, the beneficiary form that overrides your will, the free credit freeze, six questions before you buy gold, and the family code word that is said, never written.
- p. 27Three missed years of pension splitting you may be able to claim now. C$3,190 for our example couple. The CRA decides whether to accept it.
- p. 28Why “just change it online” is the wrong answer, and the form that goes by mail instead.
- p. 32Pension splitting every year from now on: C$1,182 a year for our example couple.
- p. 42Ontario’s up-to-C$1,000 hearing-aid help, and the one mistake that makes it pay nothing.
- p. 46The 100-day fill: two-thirds fewer pharmacy fees on the same medicines.
- p. 54Your bank pays 0.01%. The same-counter move worth C$325 a year to our example couple, still CDIC-insured.
- p. 66The C$25 TV package the rules require your provider to offer.
- Part TwoEleven moves that guard what you keep: the C$100,000 line and the nine CDIC categories, the beneficiary form that overrides your will, freezing or locking your credit, six questions before you buy gold, and the family code word that is said, never written.
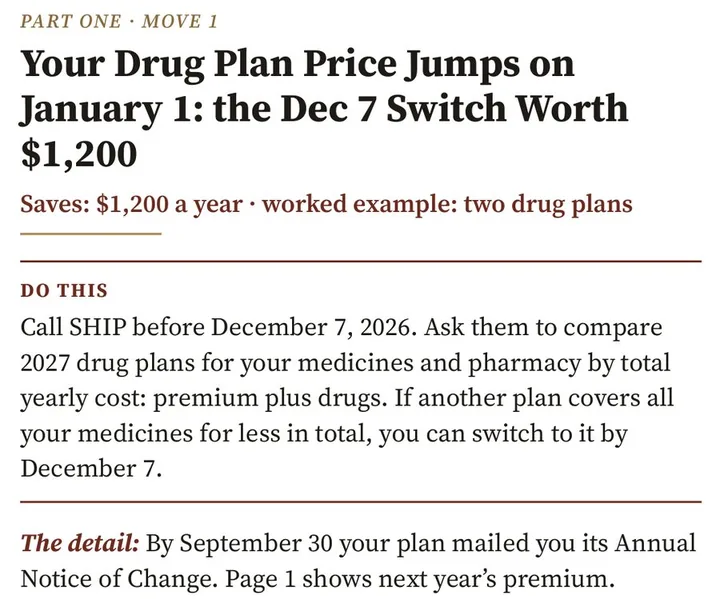
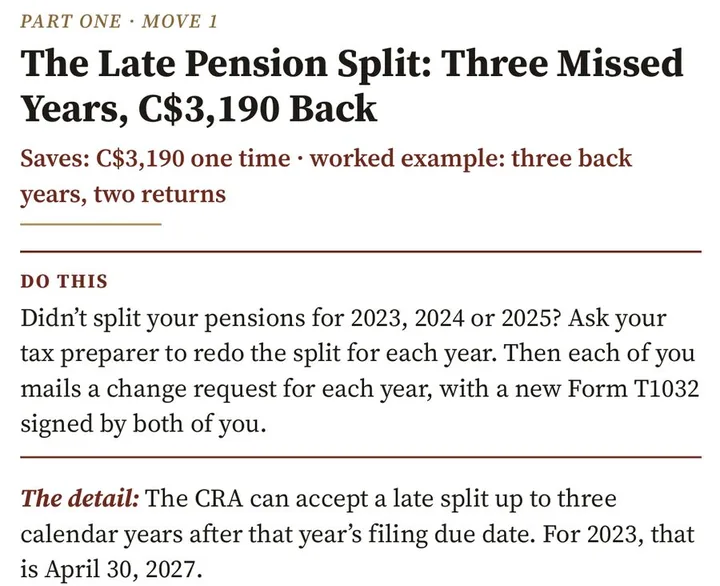
Move 1, exactly as printed. Large 18-point type throughout.
Instant access · Pay once · Yours forever
V.
The Guarantee
Earn the $47 back in your first month. Or get every penny back.
Use the manual for 30 days. If it hasn’t shown you how to earn back the $47, or for any reason at all, email homefrontmanualsupport@gmail.com from the email you paid with, and you get every penny back. No reason needed. No questions asked.
VI.
Questions
Before you order.
How do I get it? I’m not good with computers.
Right after you pay, you can download it, and an email with your link arrives too. Keep that email. It opens on any phone, tablet or computer; spread two fingers on the screen to make the print bigger. Prefer paper? Print it at home on ordinary Letter paper, or at a library or print shop. Nothing comes in the mail.
Isn’t this information free online?
The rules are public. But they’re scattered across dozens of agency websites, rate guides and federal filings, and none of them tells you which ones matter for a retired household, the deadline, or the catch. The manual puts it all in one place, in order, checked October 2026.
The videos are free. Why pay for the manual?
The videos explain what’s happening in the world. The manual is what you do about it at your own kitchen table: every rule, every deadline and every step, in one place you keep.
Do I have to give anything up?
No. Same doctor, same brands, same phone, same channels. You keep what you have and stop overpaying for it.
Can my wife or husband use it too?
Yes. One purchase covers your household. Many moves work best done together, and the Family Workbook is made to fill in side by side.
I’m widowed, or I live alone. Is it still worth it?
Yes. Every Save move shows what it’s worth for one person. For example: the hearing-aid rule $2,820 on your own pair, the home-insurance price list $400, the cable fees $240, free tax filing $220, the drug-plan window $600 a year.
Yes. Every Save move shows what it’s worth for one person. For example: Ontario’s hearing-aid help up to C$1,000 on your own pair, the internet price C$240, the C$25 TV package C$167, one phone line C$132.
I’m on Medicare Advantage. Is this for me?
Yes. The manual shows Advantage members how to get the same free total-cost check on their plan, and most of the money moves have nothing to do with your Medicare plan at all: insurance, taxes, phones, TV, internet, groceries and car service.
I don’t live in MarylandOntario.
Most moves work in every state. Where a rule depends on your state, the move carries an “In other states” box with what we confirmed, or the exact question to ask.
The tax moves are federal rules (our figures use federal and Ontario tax rates). Where a rule is provincial, the move carries an “In other provinces” box.
I don’t live in the US or Canada.
Then this manual isn’t for you. Every move is written for US or Canadian rules and deadlines.
Will anyone call me or try to sell me more?
No. One payment. No subscription. No phone calls from us.
Is this financial advice?
No. It’s education: the official rule, the deadline and the free helper for each move. The decision stays yours.
I heard a different price in an older video.
Older videos describe our First Edition. This Second Edition replaces it, with new, deeper moves and a rebuilt Family Workbook. The launch price is $47 until October 31.
The Home Front Manual · 2026–2027 Edition
They’ll keep fighting. The money on the table won’t wait.
You’re ordering the US Edition. You’re ordering the Canadian Edition.
Get the Manual · $47 →Instant access · Pay once · Yours forever
Secure checkout · PayPal · Visa · Mastercard · 30-day refund
P.S. The Medicare drug-plan window closes on December 7, and free counselor appointments fill up late in the season. That one move is worth $1,200 a year to our example couple.The hearing-aid rule alone is worth $2,820 on one pair. It’s on page 37.If one of you gets most of the pension, the late split comes first: mail by November 30 so all three years’ refunds can arrive within 12 months. The CRA decides whether to accept it.If one of you gets most of the pension, the 2023 split must reach the CRA by April 30, 2027. The CRA decides whether to accept it. Earn the $47 back in your first month, or get every penny back.